The LifeLock reviews that help shoppers do not lead with the brand name. They lead with the credit line-item: on the new plans, Core is two-bureau; Advanced and Total are three-bureau. Buy the wrong rung and you paid for identity theater without full credit coverage. That is the angle this guide uses.
LifeLock (Gen Digital / Norton family) sells identity monitoring, U.S.-based restoration specialists, high reimbursement marketing packages, data-broker removal, and—on higher rungs—scam reimbursement plus home title / investment monitoring. It is not a credit bureau, not a FICO lab, and not a substitute for free credit freezes.
Related: Aura all-in-one suite, TransUnion Premium, Equifax monitoring, best credit monitoring, credit freeze.
Education only—not a quote, loan advice, or fraud-prevention guarantee.
What’s new: Core / Advanced / Total replaced the old ladder
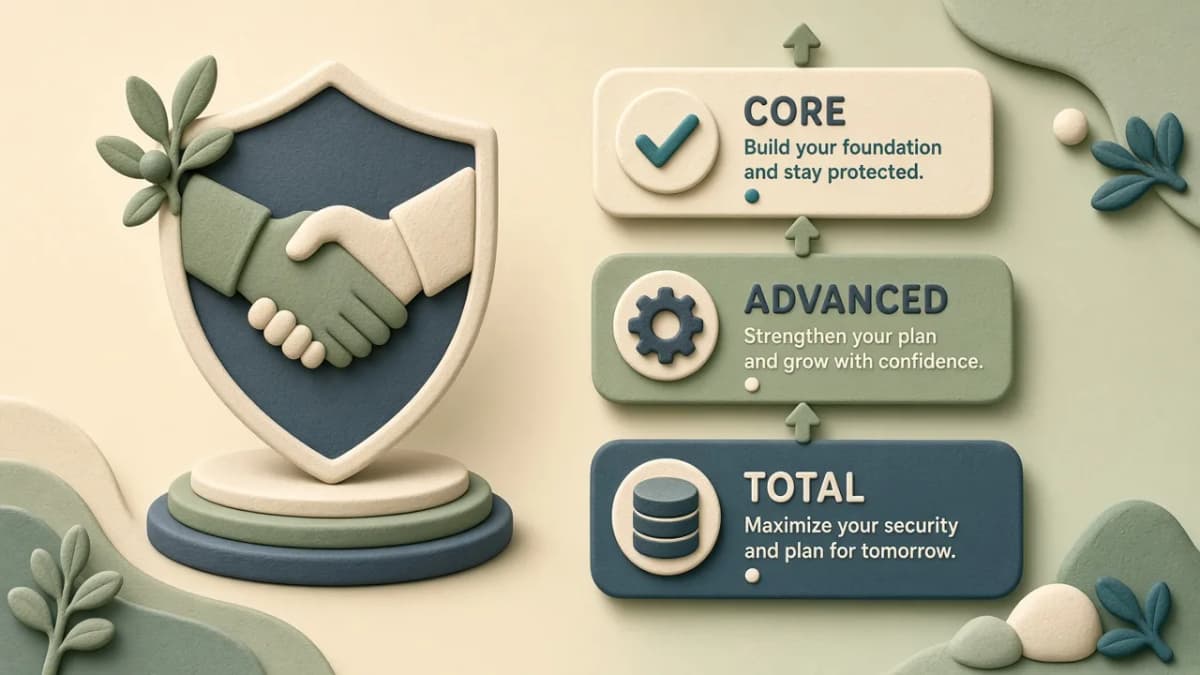
In 2026 LifeLock launched Core, Advanced, and Total—explicit upgrades over the legacy homepage names Standard, Advantage, and Ultimate Plus (those older SKUs remain for some existing subscribers until term end; they are no longer the homepage default).
LifeLock’s own “new plans” page highlights:
- Automatic data broker removal on all new plans
- Scam support + reimbursement on Advanced ($5K) and Total ($10K)—with state exclusions (e.g. New York noted in LifeLock footnotes)
- 24/7 virtual assistant for scam detection help
- Identity consultation call on Total
- Upgraded financial account alert limits (2 → 5 → unlimited)
- Credit monitoring that steps from 2-bureau (Core) to 3-bureau (Advanced/Total)
Separate Norton 360 with LifeLock bundles (Select / Ultimate Plus style device + ID combos) still appear in some funnels. Treat those as a different product family—device counts and renewal jumps differ. This review focuses on the LifeLock Core / Advanced / Total ladder on lifelock.com.
Individual pricing (confirm live)
Prices below match LifeLock’s public Individual cards as retrieved for this article. Family / 2-adult cards cost more. Promos and renewals change.
| Plan | Annual (listed) | Monthly (listed) | Credit monitoring | Headline reimbursement* |
|---|---|---|---|---|
| Core | ~$124.99/yr (~$10.42/mo) | ~$12.49/mo | 2 bureau | Up to $1.05M |
| Advanced | ~$199.99/yr (~$16.67/mo) | ~$19.99/mo | 3 bureau | Up to $1.2M + $5K scam |
| Total | ~$349.99/yr (~$29.17/mo) | ~$34.99/mo | 3 bureau | Up to $3M + $10K scam |
*Reimbursement packages are insurance benefits with lawyers/experts + stolen funds / personal expense buckets that vary by tier—read LifeLock’s legal/policy pages. LifeLock markets a 100% restoration guarantee (specialist fixes it or money back—terms apply) and 60-day money-back on eligible annual plans.
Norton-bundled LifeLock plans historically showed large year-two jumps on some SKUs. On the new Core/Advanced/Total annual cards LifeLock currently shows renewing at the same annual list price—but always screenshot renewal language before you pay.
The credit catch: when three-bureau monitoring starts
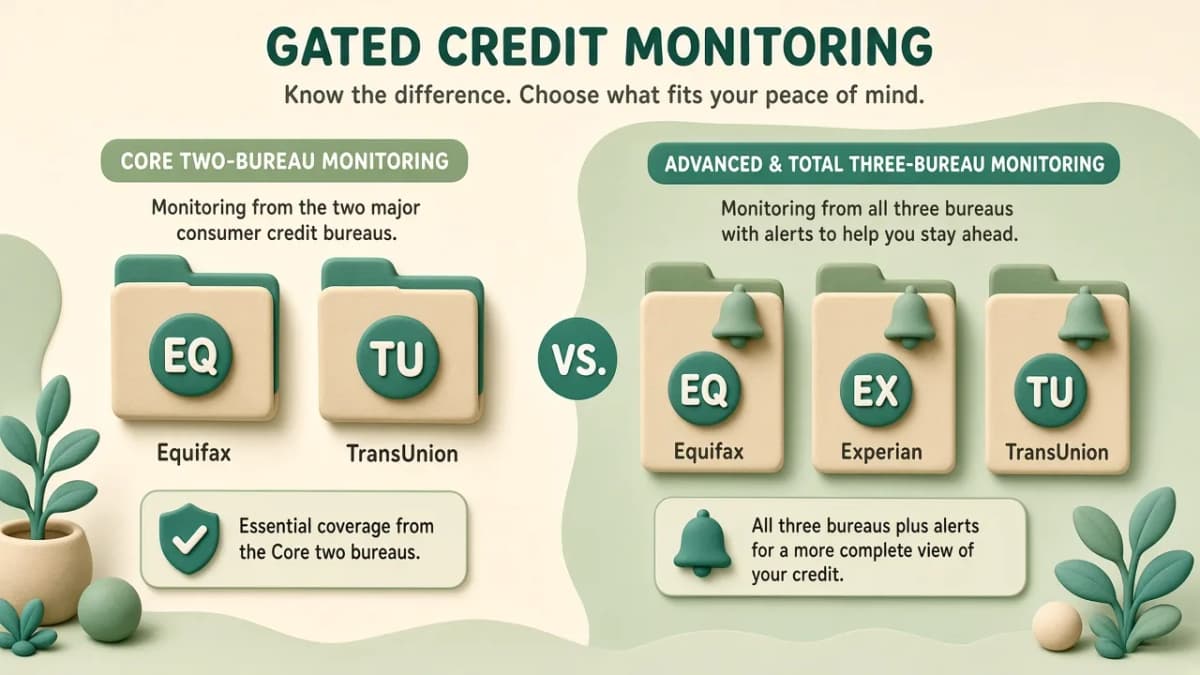
Per LifeLock’s new-plan matrix:
| Feature | Core | Advanced | Total |
|---|---|---|---|
| Credit monitoring | 2 bureau | 3 bureau | 3 bureau |
| Credit report & score access | 1 bureau monthly | 3 bureau annually + 1 bureau monthly | 3 bureau annually + 1 bureau daily |
| Credit / payday loan lock | Included | Included | Included |
| Bank/credit activity alerts | Up to 2 accounts | Up to 5 | Unlimited (+ 401k/investment on Total) |
| Home title monitoring | — | — | Included |
| Bank account takeover / phone takeover / checking app alerts | — | — | Included (Total tier) |
| Scam reimbursement | — | Up to $5,000 | Up to $10,000 |
| Identity consultation | — | — | Included |
Credit features require identity verification and can take several days to activate after enrollment (LifeLock footnote).
Score nuance: Expect VantageScore-style educational scores in many LifeLock credit experiences—not a full myFICO lab. Confirm in-app. For free FICO habits, keep CreditWise.
Lock nuance: LifeLock markets credit and payday loan locks. Locks are not stronger than freezes and do not replace freezes at all three bureaus. See lock vs freeze.
What each rung is actually for
LifeLock Core — essentials (not full three-bureau credit)
Best when LifeLock’s copy says you are early in your financial life with a few checking/credit accounts.
You get identity alerts, dark web / breach-style monitoring, social media monitoring, data broker removal, 2-bureau credit monitoring, monthly one-bureau score/report habit, up to 2 account activity alerts, credit/payday locks, restoration specialists, and ~$1.05M reimbursement marketing.
Skip Core if your comparison shopping criterion is “three-bureau credit monitoring.” That job starts at Advanced.
LifeLock Advanced — the three-bureau credit rung for most buyers
Best when you have multiple bank/credit accounts and want 3-bureau credit alerts plus scam reimbursement up to $5K and priority support.
This is the plan to price against Aura Individual ($12/mo annual list with 3-bureau on every adult plan) and TransUnion Premium ($29.95/mo).
LifeLock Total — complex finances + maximum marketing package
Best when you have property, investments/401(k), and want unlimited account alerts, home title monitoring, bank/phone takeover monitoring, daily one-bureau credit access, identity consultation, up to $10K scam reimbursement, and up to $3M identity theft package marketing.
Only buy Total if you will use those extras—otherwise Advanced usually wins the three-bureau job at a lower price.
Restoration and insurance theater (read the fine print)
LifeLock’s brand strength is restoration specialists and large reimbursement marketing:
- U.S.-based restoration on all new plans
- “Million Dollar Protection Package™” style coverage that scales by tier (lawyers/experts + stolen funds + personal expenses—buckets differ)
- Scam reimbursement on Advanced/Total (not Core), with geographic exclusions
- 100% restoration guarantee marketing (or money back—terms apply)
Insurance benefits are issued by third parties. Gen Digital notes it is not a licensed insurance producer for scam benefits in some disclosures. Read the Summary of Benefits before you treat headline millions as cash in hand.
Who LifeLock is for
Strong fit
- You want a named restoration specialist brand and will call them if fraud hits
- You need Advanced or Total for true three-bureau credit monitoring
- Scam reimbursement + data broker removal matter to you
- You already live in the Norton/LifeLock ecosystem and want one Gen Digital bill (compare Norton-bundled SKUs carefully)
- Family coverage for adults + children is worth the Family card pricing
Poor fit
- You only need free score habits → Credit Karma, CreditWise
- You want three-bureau credit on the cheapest plan → Aura advertises that; LifeLock Core does not
- You want a bureau-native monitor → TransUnion Premium / Experian / Equifax
- You refuse freezes and think $3M marketing replaces prevention
- You will buy Core for “LifeLock brand” and assume Experian+Equifax+TransUnion are all watched
LifeLock vs Aura vs TransUnion Premium
| LifeLock Advanced | Aura Individual | TransUnion Premium | |
|---|---|---|---|
| Typical annual Individual | ~$12/mo annual list | ~$29.95/mo | |
| 3-bureau credit | Yes (Advanced+) | Yes (all adult plans) | Yes (Premium) |
| Entry plan credit | Core = 2 bureau | Individual = 3 bureau | Essentials = TU only (free) |
| Device VPN/AV | Separate Norton bundles | Included | Not the focus |
| Restoration brand | Very strong | Strong U.S. remediation | Bureau specialist on Premium |
| Scam reimbursement | Advanced/Total | Via ID insurance terms | Policy-based ID expense insurance |
| Best for | Brand + scam extras + tiered credit | All-in-one value | Bureau-native paid monitor |
How to buy LifeLock without wasting money
Freeze Equifax, Experian, TransUnion
Same afternoon. See credit freeze guide.
Decide if three-bureau credit is required
If yes, skip Core—start at Advanced (or Total for property/investments).
Pick Individual, 2-adult, or Family by headcount
Do not pay Family rates for one adult.
Screenshot first-year and renewal prices
Especially if a Norton 360 bundle is in the cart.
Use the 60-day annual MBG window
Confirm eligibility. Cancel if you are not opening alerts.
Cancel overlapping Aura / bureau Premium / Norton stacks
One paid identity suite is enough for most households.
Pros and cons
Pros
- Strong restoration-specialist brand and guarantee marketing
- Clear new ladder: Core / Advanced / Total
- Three-bureau credit on Advanced and Total
- Scam reimbursement on Advanced/Total (where available)
- Data broker removal on all new plans
- High reimbursement package marketing (up to $3M on Total)
- Family and multi-adult options
- Credit / payday loan locks
Cons
- Core is only two-bureau for credit monitoring
- Often more expensive than Aura for similar three-bureau + ID jobs
- Norton-bundled SKUs can hide device/ID overlap and renewal surprises
- Score access is educational—not a FICO mortgage lab
- Insurance/scam benefits have exclusions and third-party underwriting
- Brand loyalty is not a strategy—compare the credit line-item
Common mistakes
- Buying Core assuming three-bureau credit
- Comparing LifeLock to Aura on brand fame instead of 3-bureau + price
- Ignoring renewal language on Norton bundles
- Skipping freezes because “LifeLock is watching”
- Running LifeLock and Aura and TransUnion Premium
- Paying Total for home-title/401k extras you will never open
Bottom line
LifeLock is the identity brand to buy when you want restoration specialists, scam extras, and—critically—you pick Advanced or Total for three-bureau credit. Do not buy Core for a three-bureau job. Default stack remains freezes + free score apps. Price Advanced against Aura and TransUnion Premium the same week, keep one paid suite, and cancel if alerts go unread.
Compare LifeLock Core, Advanced, and Total →
Does LifeLock Core include three-bureau credit monitoring?
No. LifeLock’s new-plan materials state Core includes two-bureau credit monitoring. Advanced and Total include three-bureau monitoring.
What happened to Standard, Advantage, and Ultimate Plus?
LifeLock replaced the homepage ladder with Core, Advanced, and Total. Existing legacy subscriptions can continue until term end; you can upgrade to a new plan.
LifeLock vs Aura—which is better?
Aura puts three-bureau credit on every adult plan and bundles VPN/AV/passwords at a lower Individual annual list price on many quotes. LifeLock wins on restoration brand, scam reimbursement rungs, and Total’s property/investment extras. Compare the credit line-item and renewal price.
Does LifeLock replace a credit freeze?
No. Freeze Equifax, Experian, and TransUnion for free. Use LifeLock for monitoring and restoration.
Is the $3 million coverage a cash guarantee?
No. It is a reimbursement/insurance marketing package with buckets, exclusions, and third-party underwriting. Read the policy summary.
Do I need Norton 360 with LifeLock?
Only if you want Gen Digital device security in the same ecosystem. The Core/Advanced/Total identity plans are separate from Norton 360 bundles—do not double-pay for overlapping tools.
Sources and notes
- LifeLock, Official plans, Meet the new LifeLock plans, Products.
- LifeLock legal / Summary of Benefits footnotes on reimbursement and scam coverage.
- Third-party pricing explainers comparing legacy vs new plans and Norton bundles (verify live).
- CFPB freeze guidance; AnnualCreditReport.com.
- Prices, bureau counts, and insurance limits change—confirm at checkout.
- This article does not guarantee fraud prevention, restoration outcomes, or insurance payouts.