The useful “best credit monitoring” roundups online in 2026 do not crown one logo for everyone. They separate three jobs—block, watch, and build—then match tools to each job. That is how this long guide is built.
Short answer: Freeze Equifax, Experian, and TransUnion for free first. For paid three-bureau credit + identity from a major bureau, start with TransUnion Credit Premium (~$29.95/mo) or free Credit Essentials if you only need TransUnion alerts. For free everyday tracking, stack Credit Karma + CreditWise (and optionally SoFi or Chase). For all-in-one non-bureau value, price Aura. For loan-prep FICO versions, use myFICO short-term. For building history, use Credit Strong (or a cheaper secured card)—that is not monitoring. None of these replace a free credit freeze.
Related deep reviews: TransUnion · Credit Strong · SoFi · Credit Karma · CreditWise · Chase Credit Journey · Experian · Equifax · Aura · LifeLock · myFICO · credit freeze · credit utilization · build credit with no history.
This is education—not a claim that any service stops every form of identity theft, and not credit-repair advice.
Table of contents
- How we chose (methodology)
- Three jobs most lists confuse
- Quick picks by category
- Master side-by-side table
- FICO vs VantageScore (why your apps disagree)
- The free stack that covers more ground
- Paid three-bureau suites compared
- Deep profiles: all 11 tools
- Scenario decision guide
- Free vs paid: when paying is rational
- Setup checklist (60 minutes)
- Common mistakes
- FAQ
- Sources
How we chose (methodology)
Independent 2026 roundups (Aura’s own app guides, SecurityHero-style multi-month tests, WealthWise/NerdWallet-style explainers, three-bureau consensus pieces) keep landing on the same truths:
- No free app monitors all three bureaus every day. Credit Karma covers Equifax + TransUnion; CreditWise covers TransUnion FICO + TU/Experian alerts; Experian Free covers Experian FICO; Chase/SoFi lean one bureau.
- Three-bureau credit is often gated. LifeLock Core is two-bureau; Advanced/Total are three-bureau. Aura puts three-bureau credit on every adult plan—that is why value roundups love it.
- Bureau Premiums compete on report cadence and brand trust. TransUnion Premium markets daily 3-bureau alerts + quarterly 3-bureau reports; Equifax Premier often markets annual full 3-bureau pulls with daily Equifax-first access; Experian Premium is the Experian-shell 3-bureau + ID rung.
- myFICO is a score lab, not the cheapest ID suite. Buy it for industry FICO versions before a loan; cancel after.
- Freezes beat unpaid “peace of mind.” CFPB/FTC guidance: freezes are free and block many new-credit pulls. Monitoring is reactive.
What we weighted for this site
| Factor | Why it matters |
|---|---|
| Job clarity (monitor vs ID vs builder) | Wrong product wastes money |
| Bureau coverage & score model | Gaps and FICO/Vantage mismatch cause false confidence |
| Free tier strength | Most households should start at $0 |
| Paid 3-bureau + restoration/insurance | Only when you will open alerts |
| Report refresh cadence | Annual vs quarterly vs monthly changes the product |
| Lock vs freeze honesty | Paid locks can unlock when you cancel |
| Our affiliate focus | TransUnion Premium / Essentials and Credit Strong are highlighted where they fit—not for every job |
We do not claim laboratory alert-speed rankings. We do claim you should buy by job after freezing.
Three jobs most lists confuse
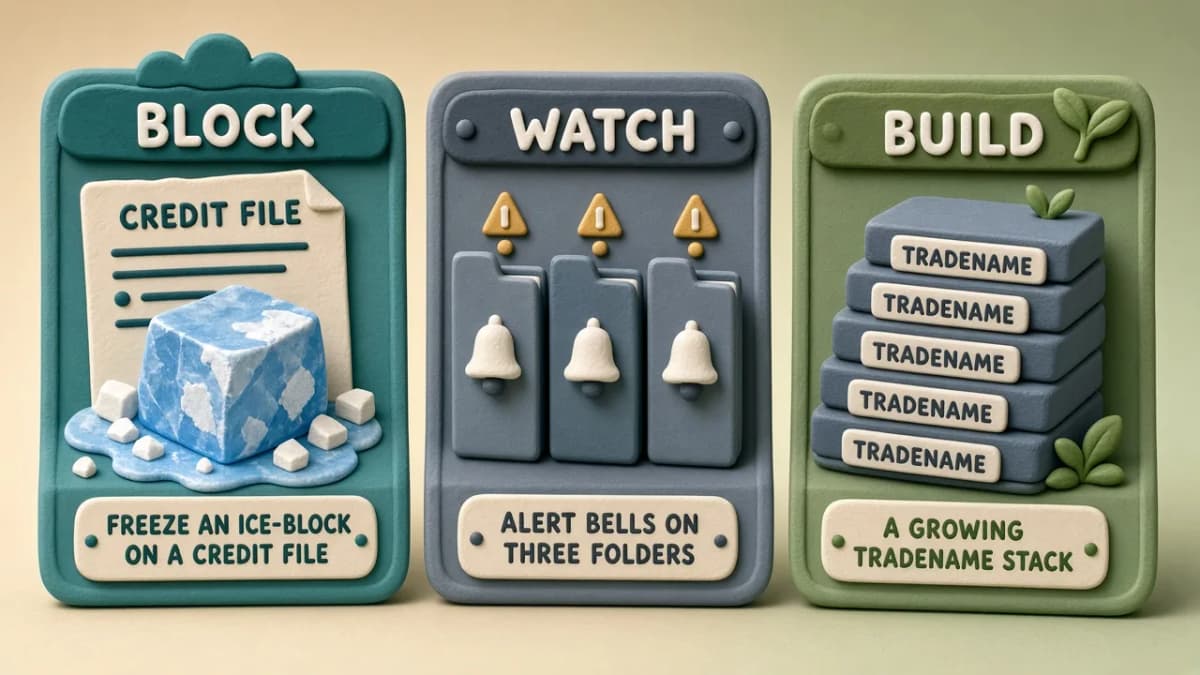
| Job | What it does | What it does not do | Typical tools |
|---|---|---|---|
| Block | Stops many new credit pulls | Does not erase existing fraud or raise scores | Free credit freezes at EQ/EX/TU; fraud alerts |
| Watch | Alerts when files/dark web change | Does not block new accounts by itself | Free apps; bureau Premium; Aura; LifeLock Advanced+ |
| Build | Adds reported payment history | Is not “monitoring”; late pays hurt | Secured card; AU status; Credit Strong |
| Your situation | Usually best first move |
|---|---|
| Block fraudulent new accounts | Freeze all three bureaus today |
| See all three reports this week | AnnualCreditReport.com (free weekly) |
| Free habit tracking / score trend | Credit Karma + CreditWise (+ SoFi/Chase optional) |
| One paid dashboard: 3-bureau alerts + ID tools | TransUnion Premium, Experian Premium, Equifax Premier, Aura, LifeLock Advanced/Total |
| Lender-style FICO depth | myFICO or Experian Core/Premium |
| Add reported payment history | Credit Strong or a cheaper secured card / credit-union builder |
Quick picks by category (2026)
| Category | Pick | Why |
|---|---|---|
| Best bureau-backed paid monitor (our affiliate focus) | TransUnion Credit Premium | Daily 3-bureau alerts, quarterly 3-bureau reports/scores, dark-web/ID tools; free Essentials tier |
| Best free dual-bureau habit app | Credit Karma | Free Equifax + TransUnion VantageScores and alerts (Experian gap remains) |
| Best free FICO-style tracker | Capital One CreditWise | Free TransUnion FICO Score 8 + TransUnion/Experian change alerts |
| Best free one-bureau + money dashboard | SoFi credit score monitoring | Free TransUnion VantageScore tools inside SoFi’s money app |
| Best free Experian-leaning bank tool | Chase Credit Journey | Free Experian VantageScore 3.0 tools + change explainer; no Chase account required |
| Best bureau FICO + CreditLock path | Experian memberships | Free Experian FICO + Boost; paid rungs add CreditLock, money tools, or 3-bureau ID |
| Best lower-cost bureau 3-bureau plan | Equifax Complete Premier | Often ~$20–$30/mo after promo; confirm annual report cadence |
| Best all-in-one ID suite (non-bureau) | Aura | 3-bureau credit on every adult plan + VPN/AV/password + data-broker removal |
| Best Norton-ecosystem ID brand | LifeLock | Core = 2-bureau; Advanced/Total = 3-bureau + scam reimbursement |
| Best FICO score laboratory | myFICO | Free EQ FICO 8; paid tiers add industry scores and 3-bureau FICO—cancel after the loan |
| Best credit-builder (not a monitor) | Credit Strong | Reports installment/revolving tradelines to all three bureaus |
Check TransUnion Credit Essentials or Premium →
Master side-by-side: 11 services
Prices below are typical public list prices as of late 2026 research—always confirm at checkout. “Score type” is what you see in the app, not what every lender uses.
| Service | Type | Typical cost | Bureaus watched | Score you usually see | ID / insurance angle |
|---|---|---|---|---|---|
| TransUnion | Bureau monitor | Free Essentials · ~$29.95/mo Premium | TU free · 3-bureau on Premium | VantageScore 3.0 | Premium: dark web, specialist, up to $1M expense insurance |
| Experian | Bureau monitor | Free · Core ~$4.99 · Premium ~$29.99 | Experian free · 3-bureau paid | FICO Score 8 (Experian) | CreditLock, ID tools, up to ~$1M on Premium |
| Equifax | Bureau monitor | Monitor ~$4.95 · Complete ~$9.95 · Premier ~$20–$30 | 1-bureau lower · 3-bureau Premier | VantageScore 3.0 | Premier: broader ID; often annual 3-bureau reports |
| Credit Karma | Free monitor / marketplace | Free (ad-supported) | Equifax + TransUnion | VantageScore 3.0 | Basic ID/breach tools; product offers |
| CreditWise | Free bank tool | Free | TU report · TU + Experian alerts | TransUnion FICO 8 | Dark-web / SSN-style alerts |
| SoFi | Free fintech tool | Free | TransUnion-focused | TransUnion VantageScore | Score + Coach money dashboard |
| Chase Credit Journey | Free bank tool | Free | Experian-focused | Experian VantageScore 3.0 | Change explainer + Experian plans |
| Aura | Paid ID suite | ~$12/mo annual Individual | 3-bureau on all adult plans | Monthly VantageScore | VPN/AV/passwords + data removal + $1M/adult |
| LifeLock | Paid ID suite | Core ~$125/yr · Advanced ~$200 · Total ~$350 | 2-bureau Core · 3-bureau Advanced/Total | Educational Vantage-style | Restoration + up to $3M / scam $5K–$10K |
| myFICO | Score-first paid | Free · $19.95 · $29.95 · $39.95 | 1-bureau Free/Basic · 3-bureau Advanced/Premier | Multiple FICO Scores | ID/insurance on Basic+ |
| Credit Strong | Credit builder | ~$15–$28+/mo (+ fees/interest) | Reports to all 3 (not a watch product) | Often monthly FICO 8 on some plans | Some higher tiers add monitoring extras |
FICO vs VantageScore: why your apps disagree
| Model | Common free sources | What to remember |
|---|---|---|
| FICO Score 8 | CreditWise (TU), Experian Free, myFICO Free (EQ) | Closer to many lending decisions—but versions differ (auto, bankcard, mortgage) |
| VantageScore 3.0 | Credit Karma, SoFi, Chase Journey, many ID suites, TransUnion/Equifax consumer scores | Excellent for trends; can sit tens of points from a lender FICO |
| Industry FICO (mortgage 2/4, auto, bankcard) | myFICO paid · Experian Core+ | Buy short-term before a loan; cancel after |
Rule: Do not panic when Karma, CreditWise, and a lender soft pull disagree. Panic when you see an account or inquiry you do not recognize—then dispute and freeze.
The free stack that covers more ground
Recommended $0 stack (most households):
- Freeze Equifax, Experian, TransUnion — guide
- Credit Karma — Equifax + TransUnion VantageScores + alerts
- CreditWise — TransUnion FICO 8 + TU/Experian alerts + dark-web/SSN tools
- AnnualCreditReport.com — all three official reports on a schedule
- Optional: SoFi if you want credit inside a money dashboard; Chase Credit Journey for Experian Vantage + “what changed”; Experian Free for Experian FICO + Boost
That free combination still is not one paid dashboard with insurance and dedicated restoration—but it closes most everyday gaps without a bill.
Paid three-bureau suites compared
| If you want… | Start here | Rough list price | Watch-out |
|---|---|---|---|
| Bureau-backed 3-bureau + ID (this site’s focus) | TransUnion Premium | ~$29.95/mo | Quarterly full 3-bureau reports; VantageScore |
| Experian-shell FICO ladder → 3-bureau | Experian Premium | ~$29.99/mo | CreditLock ≠ freeze |
| Lower-cost bureau 3-bureau marketing | Equifax Premier | Often ~$20–$30/mo | Often annual full 3-bureau reports; VantageScore |
| All-in-one + 3-bureau on every adult plan | Aura | ~$12/mo annual Individual | Experian-only lock; VantageScore |
| Restoration brand + scam extras | LifeLock Advanced/Total | ~$200–$350/yr | Skip Core if you need 3-bureau credit |
| Multi-version FICO lab | myFICO Advanced/Premier | $29.95–$39.95/mo | Cancel after the loan |
1. TransUnion — best bureau-backed pick for this site
Full review: TransUnion Credit Monitoring.
Best for: People who want a major bureau brand with a real free tier and a clear paid upgrade for three-bureau alerts + identity tools.
| Plan | What you get |
|---|---|
| Credit Essentials (Free) | Daily TransUnion report & VantageScore 3.0, TransUnion alerts, score insights; no card required; no identity monitoring |
| Credit Premium (~$29.95/mo) | Everything in Essentials + daily 3-bureau alerts, quarterly 3-bureau reports/scores, dark-web/ID monitoring, resolution specialist, up to $1M expense insurance (policy terms) |
Why it wins our affiliate focus: Clear free → paid ladder, bureau-native trust, and a Premium job that matches “I want continuous three-bureau watching + restoration tools.”
Watch-outs: Premium’s full Equifax/Experian reports refresh quarterly; the score is VantageScore 3.0, not necessarily your lender’s FICO. Monitoring does not raise your score.
2. Credit Strong — credit builder, not a monitoring substitute
Goal-first guide: Credit Strong for credit building.
Best for: Thin files or rebuilders who want an installment or revolving tradeline reported to all three bureaus.
Credit Strong (Austin Capital Bank products such as Instal, MAGNUM, and Revolv) is primarily a paid credit-builder. On-time payments can help payment history / utilization math. Some higher Revolv tiers add Experian monitoring or identity extras—but buying Credit Strong only to “monitor” is usually the wrong product.
Typical entry points (confirm live):
- Instal — about $28/mo for 48 months after a small activation fee; reports ~$1,010 installment tradeline
- MAGNUM — larger/longer installment options
- Revolv — subscription revolving tradelines from roughly $15/mo / $99/year upward
Watch-outs: Interest and/or subscription fees make this expensive versus a no-annual-fee secured card or a credit-union builder loan. Late payments hurt. Wisconsin/Vermont limits may apply. Cancel strategy matters—do not keep paying forever after you have cheaper revolving credit.
3. SoFi credit score monitoring — free TransUnion habit tool
Detailed guide: SoFi Coach credit + money tracker.
Best for: People who want a free TransUnion VantageScore view inside a broader money dashboard (spending, net worth, debt, investments).
SoFi Coach (evolution of Relay / Financial Insights branding) uses TransUnion VantageScore data, typically weekly. Soft pulls for viewing should not ding your score; applying for a SoFi loan later can trigger a hard pull.
Watch-outs: One-bureau score focus. Not a full identity-protection suite. Product offers inside SoFi are sales surfaces—treat them as optional.
See SoFi credit score monitoring →
4. Credit Karma — best-known free dual-bureau app
Detailed guide: Credit Karma dual-bureau watcher.
Best for: Free Equifax + TransUnion scores, reports, and change alerts without a monthly fee. Frequently cited as the strongest free dual-bureau starting point in 2026 roundups.
Watch-outs: Experian is not monitored. Scores are VantageScore, not FICO. The app is funded by loan/card offers—useful if you shop carefully, noisy if you click everything. Soft look vs hard-pull applications are different decisions.
5. Capital One CreditWise — best free FICO-leaning tracker
Detailed guide: CreditWise free FICO Score 8 habit.
Best for: A free TransUnion FICO Score 8, TransUnion report access, alerts on TransUnion and Experian changes, plus dark-web / SSN-style alerts. No Capital One card required. Capital One states it is 100% free with no paid CreditWise tier.
Watch-outs: Equifax is the usual gap. Score is one FICO version on one bureau. Thin files may wait months for FICO 8 after the Vantage→FICO transition. Still not paid restoration/insurance.
6. Chase Credit Journey — free Experian-leaning score tool
Detailed guide: Chase Credit Journey Experian habit.
Best for: Free Experian VantageScore 3.0 access, the “why it moved / by how many points” explainer, Experian action plans, credit alerts, and opt-in identity monitoring. No Chase account required. Weekly-style refresh.
Watch-outs: Chase (and other lenders) may not use VantageScore 3.0 for decisions. Pair with CreditWise/Karma for other bureaus/models. Treat offer/consent layers carefully.
7. Experian — best free FICO + paid CreditLock path
Detailed guide: Experian Free → Premium membership ladder.
Best for: Seeing an Experian FICO Score for free (plus Boost), then upgrading only if Core/Money Plus/Premium matches a real job.
| Tier (confirm live) | Typical role |
|---|---|
| Free | Experian report + FICO, Boost, marketplace |
| Core (~$4.99/mo) | Industry scores, simulator, CreditLock |
| Money Plus (~$14.99/mo) | Cash/bill tools + credit/ID mid-tier—not 3-bureau reports |
| Premium (~$29.99/mo) | Equifax + TransUnion reports/FICO + heavy identity stack |
Watch-outs: Free is Experian-only for reports. CreditLock can unlock if you cancel paid membership—freezes do not. Money Plus is a fintech bundle, not a sneaky Premium.
8. Equifax — bureau-direct alternative
Detailed guide: Equifax Complete & Premier monitoring.
Best for: Shoppers comparing bureau plans who want Equifax-native lock/alerts or Complete Premier three-bureau marketing.
| Typical rung | Job |
|---|---|
| Credit Monitor (~$4.95/mo) | Equifax lock + daily VantageScore + alerts |
| Complete (~$9.95/mo) | Equifax monitoring + lighter ID stack |
| Complete Premier (~$20–$30/mo) | 3-bureau monitoring; often annual 3-bureau scores/reports; daily Equifax-first access |
Watch-outs: Scores are VantageScore 3.0, not FICO. Do not confuse 24/7 three-bureau alerts with daily three-bureau full reports. Promo prices vary wildly by funnel. Judge the live plan table, not the logo alone.
Visit Equifax personal products →
9. Aura — strong non-bureau all-in-one suite
Detailed guide: Aura all-in-one identity + 3-bureau credit.
Best for: Households that want three-bureau credit monitoring on every adult plan, bundled with VPN/antivirus/password tools, data-broker removal (425+ sites), title/transaction monitoring—without a bureau membership. Frequently ranked best all-in-one value in 2026 identity roundups.
| Plan | List price (confirm) | Coverage |
|---|---|---|
| Individual | ~$12/mo annual · higher monthly | 1 adult · ~10 devices · $1M/adult insurance marketing |
| Couple | ~$22/mo annual | 2 adults |
| Family | ~$32/mo annual | Up to 5 adults + unlimited kids |
Watch-outs: Monthly score is VantageScore; in-app lock is Experian-only—still freeze EQ/TU/EX. Bundled VPN/AV may be weaker than best standalone tools. Promo pricing changes often. 14-day trial / 60-day annual MBG (exclusions apply).
10. LifeLock — identity brand with tiered credit add-ons
Detailed guide: LifeLock Core vs Advanced vs Total.
Best for: People who want LifeLock’s restoration-specialist brand and will buy Advanced or Total for three-bureau credit (plus scam reimbursement on those rungs).
| Plan | Credit monitoring | Headline extras |
|---|---|---|
| Core (~$125/yr) | 2 bureau | Data broker removal; ~$1.05M package marketing |
| Advanced (~$200/yr) | 3 bureau | Up to $5K scam reimbursement |
| Total (~$350/yr) | 3 bureau | Up to $10K scam; home title; 401k/investment; up to $3M package |
Watch-outs: Do not buy Core for a three-bureau credit job. Norton 360 + LifeLock bundles are a separate product family—check renewal math. Insurance/scam benefits have exclusions. Still freeze all three bureaus.
11. myFICO — when the score model is the product
Detailed guide: myFICO Free → Premier score lab.
Best for: Mortgage or auto shoppers who want industry FICO Scores from Fair Isaac’s consumer arm—and Premier’s mortgage simulator (Score 2 & 4 framing).
| Plan | Price | Bureaus | Cadence |
|---|---|---|---|
| Free | $0 | Equifax | Monthly FICO 8 |
| Basic | $19.95/mo | Experian | Monthly + industry scores |
| Advanced | $29.95/mo | All 3 | ~Every 3 months |
| Premier | $39.95/mo | All 3 | Monthly + mortgage simulator |
Watch-outs: Overkill for everyday fraud alerts. No refunds mid-cycle. Lender may still use a different FICO version. Cancel after closing.
Scenario decision guide: which should you actually buy?
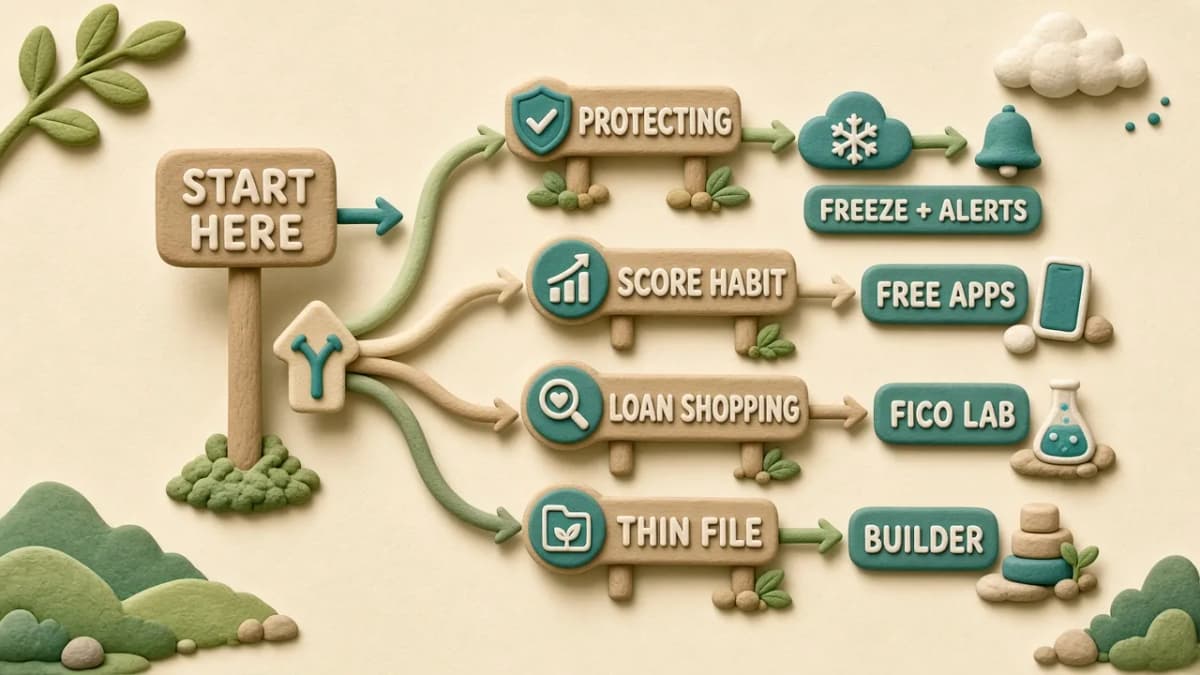
If you want maximum protection per dollar of effort
- Freeze Equifax, Experian, TransUnion (guide)
- Pull weekly reports at AnnualCreditReport.com
- Add CreditWise + Credit Karma (SoFi/Chase optional)
- Add one paid suite only if you want continuous 3-bureau alerts + insurance/resolution:
- Bureau-native → TransUnion Premium
- All-in-one value → Aura
- Restoration/scam brand → LifeLock Advanced/Total
If you only want a free score habit
Start with CreditWise (FICO 8) or Credit Karma (two VantageScores). Add SoFi or Chase Credit Journey if you already live in those apps. Add Experian Free for Boost/Experian FICO.
If your file is thin or damaged
Monitoring will not invent history. Consider a secured card, authorized-user status, or a short-term builder like Credit Strong—then monitor with a free or paid tool. See build credit with no history.
If you are 60 days from a mortgage
Prioritize myFICO Advanced/Premier or Experian industry scores + fresh three-bureau reports from AnnualCreditReport.com. Do not confuse an app VantageScore with the underwriting score. Cancel paid FICO lab access after the decision.
If you had a breach or active fraud
Freeze immediately → fraud alerts / FTC identityTheft.gov path → then consider a paid suite with restoration specialists (TransUnion Premium, LifeLock, Aura, Experian/Equifax paid) because you will actually use the help desk.
If you already pay Norton
Price LifeLock Advanced/Total against Aura before stacking. Do not pay for overlapping VPN/AV twice.
Free vs paid: when paying is rational
Stay free if:
- You will freeze all three bureaus
- You check AnnualCreditReport.com on a schedule
- You open alerts in CreditWise/Karma weekly
- You have no active fraud case
Pay if:
- You want one dashboard watching all three bureaus
- You want dark-web / resolution / expense insurance bundled
- You recently had a breach or active fraud and will use the specialist
- You need short-term industry FICO visibility for a loan (then cancel)
Paying for monitoring and skipping freezes is backwards for most households.
Rough annual cost reality check (Individual, list prices):
| Choice | Ballpark yearly |
|---|---|
| Freezes + Karma + CreditWise | $0 |
| Aura Individual annual | ~$144 |
| TransUnion Premium | ~$360 |
| LifeLock Advanced annual | ~$200 |
| myFICO Premier (if left on) | ~$480 |
| Credit Strong Instal (builder, not monitor) | Hundreds over the term—run the product math |
Setup checklist (60 minutes)
Minutes 0–15: Freeze all three bureaus
Equifax, Experian, TransUnion. Save PINs somewhere safe. Freeze guide.
Minutes 15–30: Pull AnnualCreditReport.com
Save PDFs. Circle anything unfamiliar.
Minutes 30–45: Install free watchers
CreditWise + Credit Karma. Turn on push alerts. Optional SoFi/Chase/Experian Free.
Minutes 45–55: Decide on paid (or skip)
Only if you named a job: 3-bureau ID, loan FICO lab, or builder. One paid product max for most people.
Minutes 55–60: Calendar a 60-day cancel check
If you are not opening alerts, cancel paid tools. Freezes stay.
Common comparison mistakes
- Treating Credit Strong as “monitoring” when it is mainly a builder
- Assuming SoFi / Chase / Karma cover all three bureaus
- Buying LifeLock Core for three-bureau credit
- Buying bureau Premium for a “higher score”
- Ignoring that VantageScore ≠ FICO for lending decisions
- Leaving freezes off because “I have alerts”
- Running Aura + LifeLock + TransUnion Premium forever
- Paying myFICO Premier year-round after the mortgage closed
- Trusting CreditLock more than a free freeze
- Applying for five Karma offers the week you “cleaned up” utilization
Bottom line
Use freezes for blocking, free apps for habits, and one paid three-bureau suite only when you want continuous alerts and identity backup. On this site, the bureau-backed paid path we highlight is TransUnion Credit Premium—with free Essentials if you are not ready to pay. Keep Aura in the all-in-one value lane, LifeLock Advanced/Total in the restoration/scam lane, myFICO in the short-term FICO lab lane, Credit Strong in the build-history lane, and CreditWise / Karma / SoFi / Chase / Experian Free in the free-score lane.
Deep-dive links (full reviews)
- TransUnion Credit Monitoring
- Credit Strong builder guide
- SoFi Coach credit monitoring
- Credit Karma review
- CreditWise review
- Chase Credit Journey
- Experian membership guide
- Equifax credit monitoring
- Aura identity protection
- LifeLock review
- myFICO review
- Credit freeze guide · Lock vs freeze
What is the best credit monitoring service in 2026?
It depends on the job. For a paid bureau-backed three-bureau + identity package, TransUnion Credit Premium is our highlighted pick. For free tracking, CreditWise + Credit Karma cover different bureau/model gaps. For all-in-one non-bureau value, Aura. For building history, Credit Strong is a different product category.
Is free credit monitoring enough?
Often yes—if you freeze all three bureaus, pull AnnualCreditReport.com, and open free-app alerts. Free tools do not provide full three-bureau daily monitoring or paid restoration/insurance.
Is TransUnion better than Credit Karma?
For free dual-bureau VantageScores, Credit Karma is broader than free TransUnion Essentials. For paid three-bureau alerts plus identity tools from a bureau, TransUnion Premium does a job Credit Karma does not.
Is Aura better than LifeLock?
Aura puts three-bureau credit on every adult plan and bundles device/privacy tools at a lower Individual annual list price on many quotes. LifeLock wins on restoration brand and scam reimbursement if you buy Advanced/Total—not Core. Compare the credit line-item and renewal price.
Is Credit Strong credit monitoring?
Mostly no. Credit Strong is a credit-builder that reports tradelines to all three bureaus. Some higher tiers add monitoring extras, but the core product is paid history-building, not a freeze substitute.
Is SoFi credit monitoring free?
SoFi’s credit score monitoring tools are positioned as free and use TransUnion VantageScore data. Confirm current terms on SoFi’s site; applying for SoFi credit products can involve hard pulls.
Do I need paid monitoring if I freeze my credit?
Not always. A freeze blocks many new-credit pulls. Monitoring alerts you to file changes and can add identity tools. Many people freeze for free and add paid monitoring only after a breach or if they want insurance/resolution support.
Which free app shows a FICO Score?
Capital One CreditWise is a common free option for a TransUnion FICO Score 8. Experian’s free tier and myFICO Free also show FICO Scores (Experian / Equifax respectively). Credit Karma and Chase Credit Journey typically show VantageScores.
Can credit monitoring raise my credit score?
No. Alerts do not change your file. On-time payments, lower utilization, accurate reporting, and time do.
Should I buy myFICO or TransUnion Premium?
Different jobs. myFICO is for multi-version FICO visibility around a loan. TransUnion Premium is for ongoing three-bureau alerts and identity tools. Many people use freezes + free FICO apps day-to-day, add myFICO for 30–90 days before a mortgage, and only keep a Premium/Aura suite if they want continuous ID monitoring.
What is the cheapest three-bureau credit monitoring?
Among mainstream options, Aura’s Individual annual pricing is often the lowest for three-bureau credit on every adult plan. Equifax Complete Premier sometimes markets lower bureau-native prices—confirm report cadence. Free apps never fully replace three-bureau paid monitoring.
Sources and notes
- TransUnion, Credit Essentials and Credit Premium.
- Credit Strong, product selector, Instal, FAQ.
- SoFi, credit score monitoring.
- Intuit Credit Karma, credit monitoring, free credit score.
- Capital One, CreditWise and FAQs.
- Chase, Credit Journey, free credit score.
- Experian, plans, CreditLock.
- Equifax, Complete, 3-bureau monitoring.
- Aura, pricing, identity theft protection.
- LifeLock, plans, new Core/Advanced/Total.
- myFICO, plans.
- CFPB, credit freeze explainer.
- FTC, credit freezes and fraud alerts.
- AnnualCreditReport.com.
- 2026 third-party framing referenced for competitive context (Aura app guides, multi-service test roundups, free-vs-paid explainers)—verify every vendor’s live plan page before purchase.
- This article does not guarantee score increases, fraud prevention, or insurance payouts.