The useful Experian write-ups online do not grade the brand “out of 10.” They treat it as a bureau-native membership ladder: start on Free FICO + Boost, then decide whether Core, Money Plus, or Premium earns a monthly bill. That is the angle this guide uses.
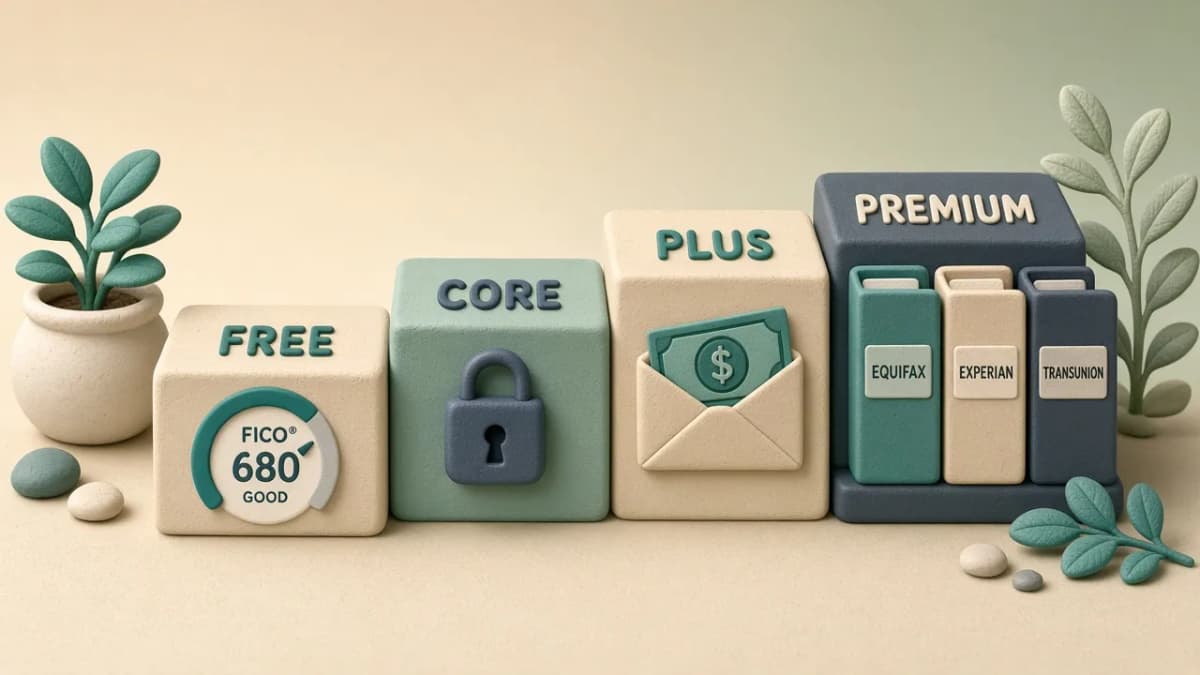
On Experian’s live plans page, the ladder is Free ($0) → Core ($4.99/mo) → Money Plus ($14.99/mo) → Premium (~$29.99/mo). Names, prices, and insurance caps move—confirm before you pay. None of these replace free security freezes at Equifax, Experian, and TransUnion.
Related: Experian / TransUnion credit lock, Chase Credit Journey, CreditWise, TransUnion Premium, best credit monitoring.
Education only—not a quote, loan advice, or fraud-prevention guarantee.
What Experian is selling (and why Free comes first)
Experian is one of the three nationwide credit bureaus. Its consumer membership product is not “just monitoring”—it is a credit + money + identity shell with an upsell path.
Experian’s own “how to choose” copy mirrors what independent reviews say:
- Most people start Free — Experian report + FICO® Score, Boost, marketplace offers, basic tools.
- Upgrade for a job, not for a logo — Core for planning/CreditLock, Money Plus for cash-flow tools, Premium for three-bureau + heavy ID.
- You can change or cancel anytime — including downgrade back to Free.
| Door | List price (as published) | Job it is selling |
|---|---|---|
| Free | $0 | Experian report + FICO Score, Boost, marketplace, basic scans |
| Core | ~$4.99/mo | Industry FICO views, simulator, CreditLock, lighter ID extras |
| Money Plus | ~$14.99/mo | Cash advances / bill tools plus credit & mid-tier ID |
| Premium | ~$29.99/mo | Equifax + TransUnion reports/FICO + heavy identity stack |
Start here: what problem are you solving?
Answer with one sentence. Then pick a door.
- “I want to see a FICO from Experian.” → Free. Stop.
- “I want industry FICO views, a simulator, and an app lock toggle.” → Core—only after you understand freezes.
- “I want cash advances / bill negotiation wrapped with credit tools.” → Money Plus—judge the money features, not the logo.
- “I want three-bureau monitoring and identity insurance in one Experian bill.” → Premium—compare to TransUnion Premium.
- “I want nobody opening new credit in my name.” → No membership required. Place free security freezes.
Door Free — take this before you tip Experian a dime
Included on Free (per Experian’s comparison table):
- Experian® credit report & FICO® Score (typically FICO Score 8 unless noted)
- Experian Boost® — add eligible positive payment history (utilities, phone, streaming, rent, insurance—rules vary)
- Marketplace surfaces (cards, loans, No Ding Decline™ offers, insurance quotes)
- One-time personal privacy scan and one-time dark-web style scan (not Premium’s ongoing stack)
- Access to freeze / fraud-alert tools Experian documents for members
- Experian Go™ credit-builder path for thin files (where offered)
- Smart Money digital checking/savings access (banking via partner bank; APY/terms vary by membership)
Why Free wins for most people
- You get a lender-familiar score brand (FICO) on the Experian file—unlike Chase Credit Journey’s Experian VantageScore.
- Boost can help some thin or score-stuck files; Experian’s own footnote says results vary and not all lenders use Boost-impacted scores.
- You can leave with $0/year spent and still freeze the file for free.
When Free is not enough
- You need Equifax + TransUnion inside Experian’s app → Premium on the current table.
- You want CreditLock’s in-app toggle → Core and above (Free lists CreditLock as not included).
- You want mortgage/auto/bankcard industry FICO views + simulator → Core and above.
Spend thirty days on Free. If you never open the app, you will not use Premium either.
Door Core (~$4.99/mo) — tools + CreditLock
Core is Experian’s pitch for credit planning before a car, home, or personal loan:
- Industry-specific FICO® Scores (mortgage, auto, bankcard style views where offered)
- FICO® Score Simulator & planning (uses your profile data; educational, not a lender promise)
- CreditLock + inquiry alerts on the Experian file
- Fraud resolution / lost-wallet assistance
- Dark web surveillance (ongoing vs Free’s one-time scan)
- Identity theft insurance marketed up to $100K (vs Premium’s up to $1M—policy terms apply)
Pay Core only if both are true:
- You will actually use the simulator / industry scores before a loan, and
- You prefer an app lock toggle enough to pay monthly—knowing a free freeze does the core blocking job.
Annualize it: ~$60/year. Cheap versus Premium; expensive versus Free + freeze if you never open Core features.
CreditLock vs freeze (read this before Core)
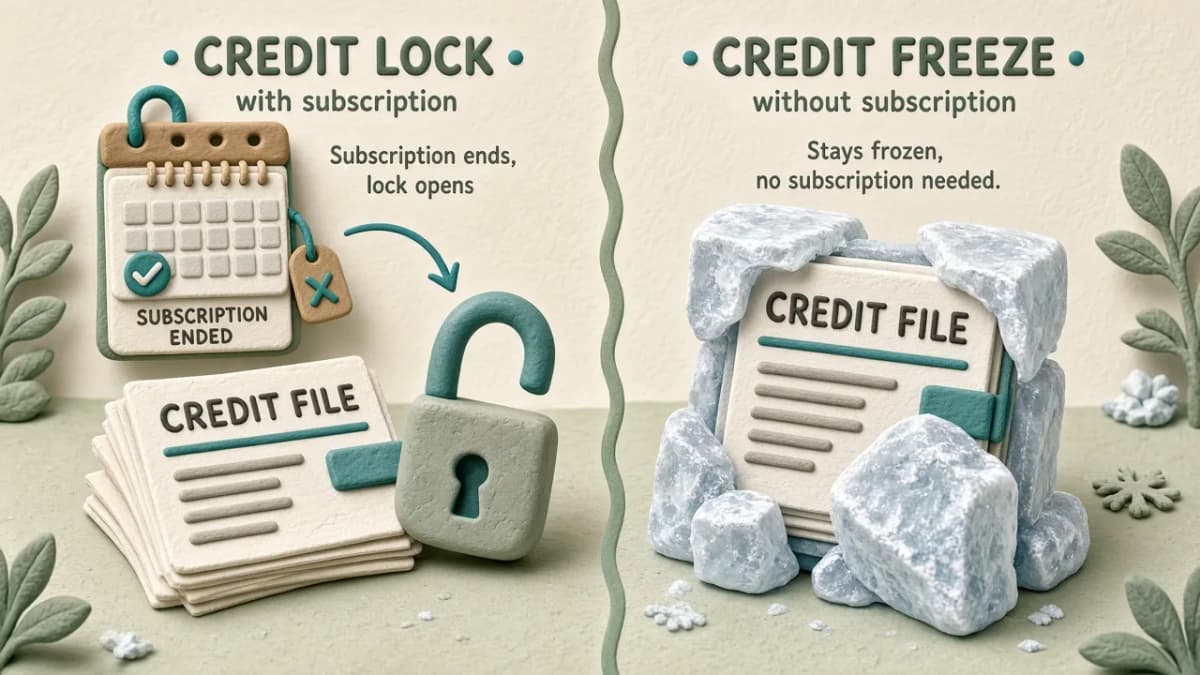
Experian’s CreditLock page and CFPB freeze guidance line up on the key points:
- Locks are no more effective than freezes at blocking new credit access.
- Freezes are free by law and stay until you lift them.
- If you cancel a paid membership while locked, Experian materials warn the file can unlock when the paid feature ends.
- CreditLock is a separate service from a security freeze.
Full walkthrough: Experian and TransUnion credit lock.
Door Money Plus (~$14.99/mo) — only if you want the money product
Money Plus is not “better Premium.” It is a different product family:
- Experian Cash™ advances powered by Brigit (~$25–$250; eligibility varies; Experian notes some advances may be available even with Free—confirm live terms)
- Bill negotiation and subscription cancellation (results not guaranteed)
- Credit/ID features including CreditLock and insurance marketed up to $500K
- Smart Money savings features (APY marketed up to tiers that can depend on membership—confirm current APY)
Important: Money Plus does not add Equifax/TransUnion reports & FICO on Experian’s table—that is Premium’s job.
Buy this door only to use cash-flow tools you would pay for anyway. If you would not open a fintech cash-advance app, skip Money Plus.
Door Premium (~$29.99/mo) — three-bureau + identity stack
Premium is the “comprehensive protection” door:
- Equifax® and TransUnion® credit reports & FICO® Scores (plus Experian)
- Broader identity stack: ongoing dark-web surveillance, SSN tracing, financial account monitoring, address-change validation, social network monitoring
- Regular personal privacy scans + auto removal help (vs one-time on lower tiers)
- Fraud resolution, lost-wallet assistance, CreditLock
- Identity theft insurance marketed up to $1 million (underwritten by third parties; exclusions apply)
- Family plan option (additional adult + children monitoring—confirm live pricing)
Rough annual cost: ~$360 before tax.
Premium makes sense when
- You want one Experian login for three-bureau visibility and ID alerts, and
- You will act on alerts, and
- You already froze (or will freeze) all three bureaus so you are not paying for a false sense of a locked door.
Premium is a bad buy when
- Your only goal is a higher score (monitoring does not raise scores).
- You already pay TransUnion/Aura/LifeLock for the same job—pick one suite.
- You refuse freezes and think insurance marketing replaces prevention.
Experian also markets separate IdentityWorks SKUs in some funnels (trial language, family pricing). Treat those as the same job family as Premium—compare the live matrix the week you buy so you do not double-pay.
See Premium / full plan matrix →
The five-minute buy-or-skip script
- My goal this quarter is: _______________________
- I already froze Equifax / Experian / TransUnion: Y / N
- I need FICO on Experian only: → Free (+ Boost if eligible)
- I need CreditLock convenience and will use simulators: → Core (or Free + freeze)
- I need cash advances / bill negotiation: → Money Plus (optional)
- I need three-bureau + ID insurance in Experian’s shell: → Premium, else compare TransUnion
- If I would cancel in 60 days, I should start on Free and upgrade later.
Experian vs Chase vs CreditWise vs TransUnion
| Experian Free | Chase Credit Journey | CreditWise | Experian Premium | TransUnion Premium | |
|---|---|---|---|---|---|
| Cost | $0 | $0 | $0 | ~$29.99/mo | ~$29.95/mo |
| Score focus | Experian FICO | Experian VantageScore 3.0 | TU FICO 8 | 3-bureau FICO views | TU + paid 3-bureau |
| Boost | Yes (Experian file) | No | No | Yes | N/A |
| CreditLock | Paid tiers | N/A | N/A | Included | Different lock products |
| Best for | Free Experian FICO habit | Change explainer + plan | Free TU FICO habit | One-login 3-bureau ID | Competing paid suite |
Vs Chase Credit Journey: Same bureau file underneath; different score brand. Journey is free Vantage + explainer; Experian Free is FICO + Boost.
Vs CreditWise: CreditWise is free TransUnion FICO 8 + TU/Experian alerts. Experian Free is Experian FICO + Experian-native tools. Complementary.
Vs TransUnion Premium: Both compete for paid three-bureau + identity dollars. Price them side by side the week you buy; do not run both forever.
How to use Experian well (any door)
Start on Free for 30 days
Confirm you can see your Experian report and FICO Score before you tip the ladder.
Try Boost only if eligible bills exist
Connect eligible accounts; expect mixed results. Not a repair scheme.
Freeze Equifax, Experian, TransUnion
Do this before paying for CreditLock. See credit freeze guide.
Upgrade only for a named job
Core = planning/lock toggle. Money Plus = cash tools. Premium = 3-bureau ID.
Calendar a 60-day cancel check
If you stopped opening alerts or simulators, downgrade to Free.
Treat marketplace offers as ads
No Ding Decline™ and matched offers are shopping tools—not fiduciary advice.
Pros and cons
Pros
- Free Experian FICO habit from a bureau-native app
- Boost and thin-file tools (Go) on Free
- Clear ladder: Core tools, Money Plus cash, Premium 3-bureau
- Industry FICO views + simulator on paid planning tiers
- Strong identity stack on Premium (insurance marketing up to $1M)
- Easy downgrade/cancel path back to Free
Cons
- Paid locks are not stronger than free freezes—and can unlock if you cancel
- Free is still Experian-only for reports/scores
- Money Plus is easy to buy for the wrong reason (thinking it is Premium)
- Marketplace pressure toward new credit products
- Insurance marketing numbers ≠ cash in your pocket—read the policy summary
- Lender may use a different FICO version than Score 8
Common mistakes
- Paying Premium to “raise your score”
- Buying Money Plus for three-bureau monitoring
- Relying on CreditLock instead of freezes at all three bureaus
- Ignoring Chase/CreditWise free tools that cover different angles at $0
- Leaving Premium on autopay after you stop opening alerts
- Expecting Boost to fix collections or late payments
Bottom line
Default to Experian Free + three freezes. Use Boost if eligible. Step to Core only for industry scores, simulator, and a CreditLock toggle you will actually use. Treat Money Plus as a fintech cash-flow bundle, not a credit upgrade. Buy Premium only when three-bureau identity monitoring in Experian’s shell is the job—and cancel if you stop opening alerts.
Compare Premium side by side with TransUnion Credit Premium the week you buy. Keep CreditWise or Chase Credit Journey only if they fill a free habit Free does not.
Start on Experian Free (or compare paid doors) →
Is Experian Free really free?
Yes for the Free membership tier: Experian report, FICO Score, Boost, and basic tools. Paid features like CreditLock and three-bureau reports sit on Core / Money Plus / Premium.
What FICO Score does Experian show?
Typically FICO Score 8 unless otherwise noted. Experian may also offer industry-specific FICO views on paid tiers. Your lender may use a different version or bureau.
Does Experian Boost guarantee a higher score?
No. Experian states results vary; not all payments are eligible; not all lenders use Boost-impacted scores.
Is CreditLock better than a freeze?
No. Freezes are free and indefinite. CreditLock is a paid convenience that can unlock if you cancel the membership feature. See our lock vs freeze guide.
Which plan has three-bureau reports?
Premium on Experian’s current membership matrix. Free/Core/Money Plus do not include Equifax and TransUnion reports & FICO in that table.
Experian Free vs Chase Credit Journey?
Both can show Experian-file insights. Journey uses VantageScore 3.0 with a change explainer; Experian Free shows FICO and Boost. Many people use one or the other—not both forever.
Experian Premium vs TransUnion Premium?
Same job family: paid three-bureau + identity. Compare live price, insurance terms, and which app you will actually open. Do not pay for both indefinitely.
Sources and notes
- Experian, Membership plans & pricing — Free / Core / Money Plus / Premium feature matrix (retrieved for this article; verify live).
- Experian, CreditLock — paid lock vs free freeze notes; unlock-on-cancel warning.
- Experian, Identity theft protection compare — related IdentityWorks-style SKUs.
- CFPB, What is a credit freeze?.
- Money Guardian USA, Experian and TransUnion credit lock.
- Plan names, prices, APYs, advance eligibility, and insurance limits change; this page is a decision framework, not a quote.
- This article does not guarantee score gains, approvals, or fraud prevention.