The myFICO write-ups that help shoppers do not sell it as “another identity suite.” They sell the rare thing Fair Isaac’s consumer arm actually owns: the FICO® Score versions lenders use—including mortgage, auto, and bankcard industry scores. That is the angle this guide uses.
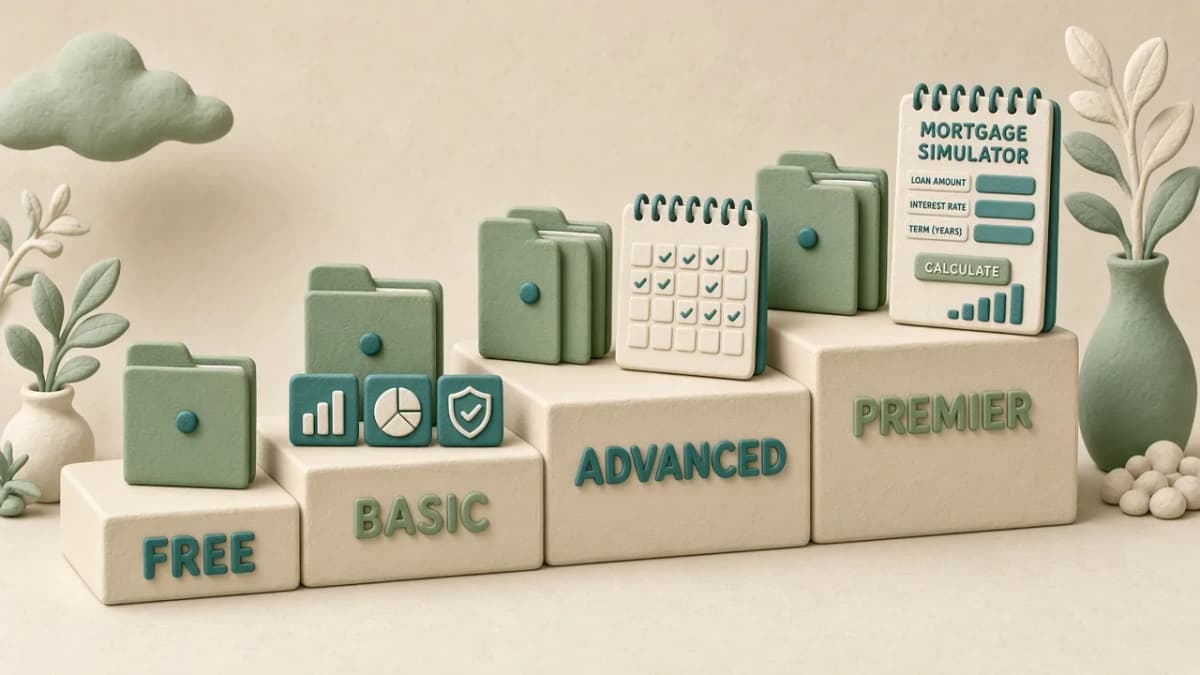
myFICO is the official consumer division of FICO (Fair Isaac). Plans run Free → Basic ($19.95/mo) → Advanced ($29.95/mo) → Premier ($39.95/mo). Buy it when you need lender-familiar FICO models before a mortgage, auto, or card decision. Do not buy it as your everyday free score habit or as a LifeLock/Aura replacement—and never skip free credit freezes.
Related: CreditWise free FICO 8, Experian memberships, TransUnion Premium, Aura, best credit monitoring.
Education only—not loan advice, credit repair, or a guarantee your lender uses the same FICO version.
Why myFICO exists (and why Vantage apps are not the same job)
FICO markets that ~90% of top U.S. lenders use FICO Scores. Free apps often show VantageScore 3.0 (Credit Karma, Chase Credit Journey, SoFi, many ID suites). Those are useful habits—but a mortgage desk may pull FICO Score 2 / 4 / 5-style industry models that never appear in a free Vantage dial.
myFICO’s pitch: get FICO Score 8 plus (on paid tiers) the mortgage, auto, and credit-card FICO versions most used for those products—from the company that builds the models.
myFICO itself warns: your lender or insurer may still use a different FICO version—or another score type altogether. Treat myFICO as the best consumer FICO lab, not an underwriting oracle.
The plan ladder (confirm live)
| Plan | Price | Bureaus | Update cadence | Signature extras |
|---|---|---|---|---|
| Free | $0 (no card required) | Equifax only | Monthly | FICO Score 8 + Equifax report + Equifax monitoring/alerts |
| Basic | $19.95/mo | Experian only | Monthly | Industry FICO scores (mortgage/auto/cards) + Score 8 simulator + up to $1M ID insurance marketing + 24x7 restoration |
| Advanced | $29.95/mo | All 3 | Every 3 months | Industry FICO scores + Score 8 simulator + identity monitoring + $1M insurance marketing |
| Premier | $39.95/mo | All 3 | Monthly | Everything in Advanced + mortgage score simulator (FICO Score 2 & 4 framing) |
Subscriptions auto-renew; myFICO states you may cancel anytime but refunds are not available. One-time report purchases also appear in some funnels (~$19.95 one bureau / ~$59.85 three-bureau—confirm live).
What each door is for
Free — Equifax FICO habit at $0
Included: Equifax FICO Score 8, Equifax credit report (monthly refresh), score/credit monitoring alerts on Equifax data.
Not included: Mortgage/auto/bankcard industry scores, Score 8 simulator, identity insurance, identity monitoring.
Use Free when you want an official FICO brand habit on Equifax without paying. Pair with CreditWise (TransUnion FICO 8) and Experian Free for other free FICO angles—still freeze all three bureaus.
Basic ($19.95/mo) — Experian industry scores + simulator
Included: Experian coverage, FICO Score 8 plus scores for mortgages/auto/cards, FICO Score 8 simulator, credit monitoring, up to $1M identity theft insurance marketing, 24x7 identity restoration.
Not included: Three-bureau coverage; mortgage-specific Score 2/4 simulator (Premier); full identity monitoring (Advanced/Premier).
Use Basic when you need industry FICO views on Experian and a Score 8 simulator but not a full three-bureau subscription. Some promos advertise a cheap first month—confirm at checkout.
Advanced ($29.95/mo) — three-bureau FICO, quarterly updates
Included: Complete 3-bureau reports/scores with updates about every three months, industry FICO scores, Score 8 simulator, credit + identity monitoring, $1M insurance marketing, restoration.
Not included: Monthly three-bureau refresh; mortgage Score 2/4 simulator.
Use Advanced when you want a tri-merge style FICO view before a loan and can live with quarterly refreshes. This is the usual “I have a mortgage appointment in 60–90 days” rung.
Premier ($39.95/mo) — monthly three-bureau + mortgage simulator
Included: Everything in Advanced, but monthly three-bureau updates, plus the FICO mortgage score simulator (actions affecting FICO Score 2 & 4 used by many mortgage lenders).
Use Premier when you are actively shopping a mortgage and will open the mortgage simulator weekly. At ~$480/year, cancel after closing unless you still need monthly tri-bureau FICO pulls.
Start Free or compare paid plans →
What myFICO is not
| Expectation | Reality |
|---|---|
| Cheapest three-bureau identity suite | Aura / LifeLock / bureau Premiums compete on ID; myFICO competes on FICO versions |
| Free FICO from all three bureaus | Free = Equifax only; 3-bureau starts at Advanced |
| Instant alerts like Aura’s marketing | myFICO notes monitoring frequency/triggers vary by bureau |
| Exact lender score guarantee | Lender may use a different FICO version or model |
| Credit repair | Fair Isaac explicitly is not a credit repair organization |
Who myFICO is for
Strong fit
- Mortgage shoppers who want FICO Score 2/4-style visibility and (on Premier) a mortgage simulator
- Auto / bankcard shoppers who want industry FICO versions, not only Score 8
- People who distrust free Vantage dials for a near-term loan decision
- Short-term subscribers who will cancel after the loan
Poor fit
- Everyday free score tracking → CreditWise, Experian Free, Credit Karma, SoFi, Chase
- Cheapest three-bureau identity monitoring → Aura / TransUnion Premium / LifeLock Advanced
- Building credit history → secured card / Credit Strong—myFICO does not invent tradelines
- Anyone who will not open industry scores and would only stare at Score 8
myFICO vs CreditWise vs Experian vs Aura
| myFICO Free | CreditWise | Experian Free/Core | myFICO Advanced/Premier | Aura | |
|---|---|---|---|---|---|
| Cost | $0 | $0 | $0 / ~$4.99+ | $29.95–$39.95/mo | ~$12/mo annual Individual |
| Score brand | Equifax FICO 8 | TU FICO 8 | Experian FICO | Multi-bureau FICO + industry | Monthly VantageScore |
| Industry FICO (mortgage/auto) | No | No | Core adds industry views | Yes | No |
| 3-bureau | No | Alerts TU+EX | Premium | Yes | Credit alerts yes |
| Best for | Free EQ FICO habit | Free TU FICO habit | Boost + Experian ladder | Loan-prep FICO lab | All-in-one ID |
Practical stack before a mortgage: Freezes → AnnualCreditReport.com → myFICO Advanced or Premier for 30–90 days → cancel → keep CreditWise/Experian Free for ongoing FICO habits.
How to use myFICO without overpaying
Freeze Equifax, Experian, TransUnion
Blocking new credit matters more than any score dashboard. See credit freeze guide.
Start on Free for a week
Confirm Equifax FICO 8 access before you tip the ladder.
Name the loan and date
Mortgage in 60 days → Advanced or Premier. Auto/card curiosity → Basic or free CreditWise first.
Pull AnnualCreditReport.com the same week
Dispute errors at the bureau—not only inside myFICO.
Use the right simulator
Score 8 simulator on Basic+; mortgage Score 2/4 simulator on Premier only.
Calendar cancel for the day after closing (or denial)
No refunds on unused days—do not leave Premier on autopay for a year.
Pros and cons
Pros
- Official FICO consumer product from Fair Isaac
- Free Equifax FICO Score 8 with no card required
- Industry FICO scores for mortgage, auto, and cards on paid tiers
- Three-bureau FICO views on Advanced/Premier
- Mortgage score simulator on Premier
- Score 8 simulator on Basic+
- ID insurance/restoration marketing on paid tiers
Cons
- Expensive vs free FICO apps for everyday use
- Free/Basic are one bureau only
- Advanced refreshes quarterly, not monthly
- Monitoring alert speed varies; not marketed as the fastest ID suite
- No refunds after cancel mid-cycle
- Lender may still use a different model
Common mistakes
- Paying Premier year-round for a score you check twice
- Buying Advanced for “identity theft” when Aura/LifeLock fit better
- Ignoring Free and jumping to $40/mo
- Treating myFICO Score 8 as your exact mortgage underwriting score without industry views
- Skipping freezes because you “have monitoring”
- Never canceling after the loan closed
Bottom line
myFICO is the right buy when the score model is the product—especially mortgage/auto prep with industry FICO versions. Default everyday stack: freezes + free FICO/Vantage apps. Use Free anytime for Equifax FICO 8; step to Basic / Advanced / Premier only for a dated loan goal; cancel when the decision is done.
For ongoing three-bureau identity alerts at a lower price, compare Aura or TransUnion Premium. For free TransUnion FICO 8, keep CreditWise.
Get myFICO Free (or compare paid plans) →
Is myFICO Free really free?
Yes. myFICO’s Free plan is $0 with no credit card required and includes an Equifax-based FICO Score 8, Equifax report access, and Equifax monitoring/alerts.
Which plan has three-bureau FICO Scores?
Advanced ($29.95/mo, updates about every 3 months) and Premier ($39.95/mo, monthly updates). Free and Basic are one-bureau.
Does myFICO show mortgage FICO Scores?
Paid plans include scores used for mortgages, auto loans, and credit cards. Premier adds a mortgage score simulator framed around FICO Score 2 and 4. Your lender may still use a different version.
myFICO vs CreditWise—which should I use?
CreditWise is the best everyday free TransUnion FICO 8 habit. myFICO is for official multi-version FICO access (and three-bureau paid tiers) around a loan decision.
myFICO vs Experian membership?
Experian Free/Core is strong for Experian-native FICO + Boost/CreditLock. myFICO is stronger when you specifically want Fair Isaac’s multi-bureau industry score lab.
Does checking myFICO hurt my score?
myFICO states checking your credit with FICO will not affect your FICO Scores (soft-look access).
Should I keep Premier after I get a mortgage?
Usually no. Downgrade to Free or cancel and keep free FICO apps plus freezes unless you still need monthly three-bureau FICO pulls.
Sources and notes
- myFICO, Home / plans, FICO score plans pricing, FICO Advanced.
- NerdWallet / MoneyLion-style explainers on plan worth (cross-checked against live myFICO matrix).
- CFPB freeze guidance; AnnualCreditReport.com.
- Plan features and prices change; refunds are not available per myFICO footnotes—confirm live.
- This article does not guarantee lender score matches, approvals, or fraud prevention.