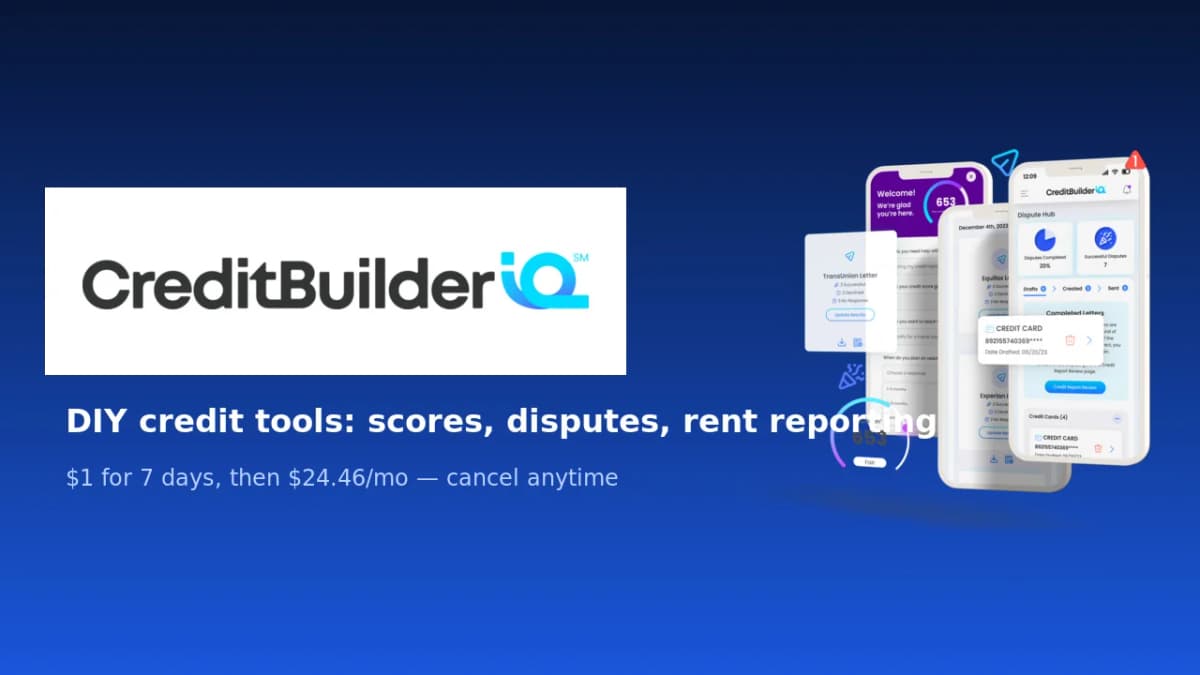
The CreditBuilderIQ pages that convert do not sell “mystery credit repair.” They sell a DIY dashboard: see all three bureau scores, let AI flag weak spots, generate dispute letters, track bureau responses, and optionally report rent and utility payments you already make—starting at $1 for 7 days, then $24.46/month, cancel anytime. That is the angle this review uses.
CreditBuilderIQ is offered by IDIQ® (Temecula, CA)—the same company family behind IdentityIQ® / MyScoreIQ® brands. It is software and reporting tools, not a secured credit-builder loan like Credit Strong, and not a promise that accurate negative items will disappear. Checking scores through the service is marketed as no hard inquiry. Pair any plan with free credit freezes at Equifax, Experian, and TransUnion.
Related: best credit monitoring, Credit Strong, build credit with no history, credit utilization, credit freeze, TransUnion Premium.
Education only—not credit repair advice. Score increases are not guaranteed. Fair credit reporting rights still belong to you whether you use software or dispute directly.
What top promoter pages emphasize (and what we keep)
We reviewed how leading CreditBuilderIQ funnels and reviews frame the product—including the official affiliate landing (creditbuilderiq.com/aff/4), high-converting promo landers (e.g. creditscoreads-style pages), walkthrough reviews (Everyday Economics–style signup guides), IDIQ’s launch announcement, and directory pricing notes (SuperMoney’s $24.46/mo verification):
| Promoter pattern | What they push | What we add for readers |
|---|---|---|
| $1 week → $24.46/mo | Low-friction trial | Calendar cancel before renewal; no refunds assumed mid-cycle |
| 3-bureau scores & reports | “See everything in one place” | Still pull AnnualCreditReport.com on a schedule |
| AI dispute letters + Dispute Hub | One-click letter generation | You must mail/send and track; accurate negatives can remain |
| Rent & utility reporting | Build without new debt | Only on-time payments; eligibility/providers vary |
| No hard inquiry / cancel anytime | Soft-look comfort | Applying for other credit later can still hard-pull |
| Identity / dark-web alerts | Extra peace of mind | Freezes still beat alerts for blocking new accounts |
Start CreditBuilderIQ — $1 for 7 days →
What CreditBuilderIQ actually is
CreditBuilderIQ is a consumer membership platform for DIY credit action:
- See three-bureau credit scores and reports
- Analyze negative/score factors with AI-assisted review
- Dispute flagged inaccuracies with generated, bureau-specific letters
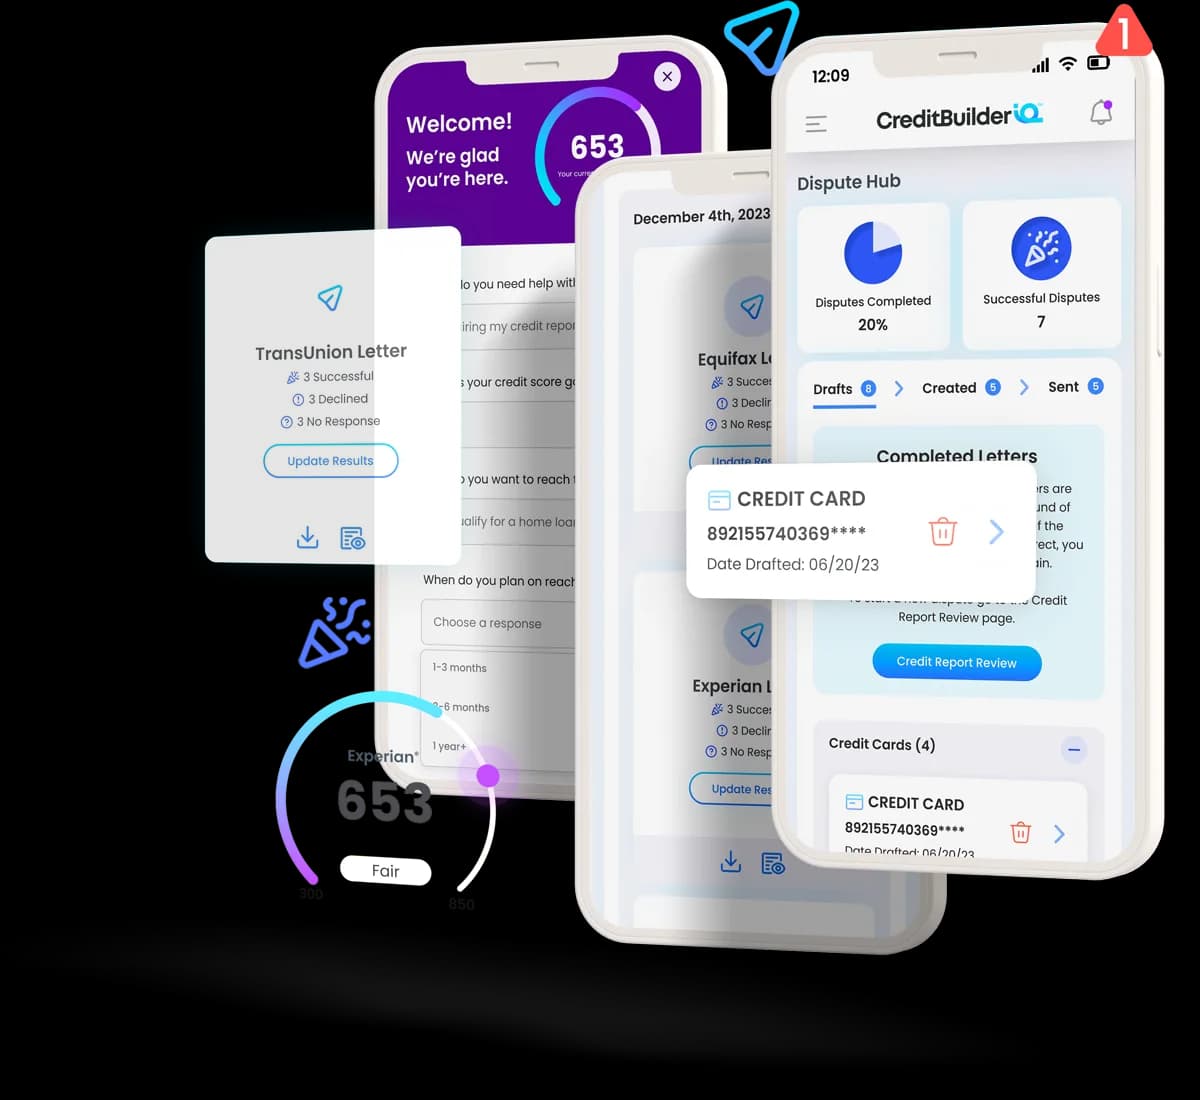
- Track letters and responses in a Dispute Hub
- Build by reporting eligible rent, utility, and subscription payments
- Watch identity / dark-web style alerts (per promo feature lists)
It is not:
- A traditional credit-repair law firm that disputes for you end-to-end
- A secured installment/revolving loan product (that is closer to Credit Strong / Self-style builders)
- A guarantee that bureaus will delete accurate late payments, collections, or charge-offs
- A substitute for freezes, on-time payments, or low utilization
IDIQ launched CreditBuilderIQ in April 2024 specifically to put “credit-building tools in the hands of consumers”—AI analysis, personalized score factors, dispute generation, 3-bureau reports/scores, and utility payment reporting in one stack.
Pricing: the $1 trial offer (confirm live)
| Phase | Price | Notes |
|---|---|---|
| Trial | $1 for 7 days | Affiliate/promo funnels (including aff/4 and creditscoreads-style pages) |
| Ongoing | $24.46/month | Verified on directory listings; cancel anytime per marketing |
| Official site plans page | Sometimes shows other SKUs (e.g. higher 3-bureau list prices) | Always trust your checkout cart—promo vs retail can differ |
Included on the $1 → $24.46 funnel (typical promo bullets):
- 3-bureau credit scores & reports
- AI-driven interactive credit analysis
- Unlimited dispute letter generation
- Full dispute tracking hub
- Score progress tracker & charts
- Identity protection & dark-web scan
Trial hygiene
- Enroll only if you will open the dashboard within 48 hours.
- Set a phone reminder for day 5 to cancel if unused.
- Screenshot the order summary (trial length, renewal price, cancel path).
- Do not expect partial-month refunds after renewal.
Claim the $1 CreditBuilderIQ trial →
Feature deep dive
1) Three-bureau scores and reports
You get a Score Center style view of Equifax, TransUnion, and Experian scores plus report access so you can spot mismatches between bureaus. Promoter walkthroughs emphasize signing up in minutes and seeing all three files in one login—something free single-app stacks often miss without juggling Karma + CreditWise + Experian Free.
Reality check: The score model shown in-app may be educational (confirm whether you see FICO, VantageScore, or both). Lenders can still pull different versions. For mortgage-prep industry FICO labs, see myFICO.
2) AI credit analysis and personalized game plan
CreditBuilderIQ markets AI that flags items negatively affecting your score and outlines score factors with a proactive game plan. That matches how Everyday Economics–style reviews describe the first dashboard: clear next steps instead of a raw PDF dump.
Use the AI as a checklist generator, not as a lawyer. Cross-check every flagged item against your official reports.
3) Unlimited dispute letters + Dispute Hub
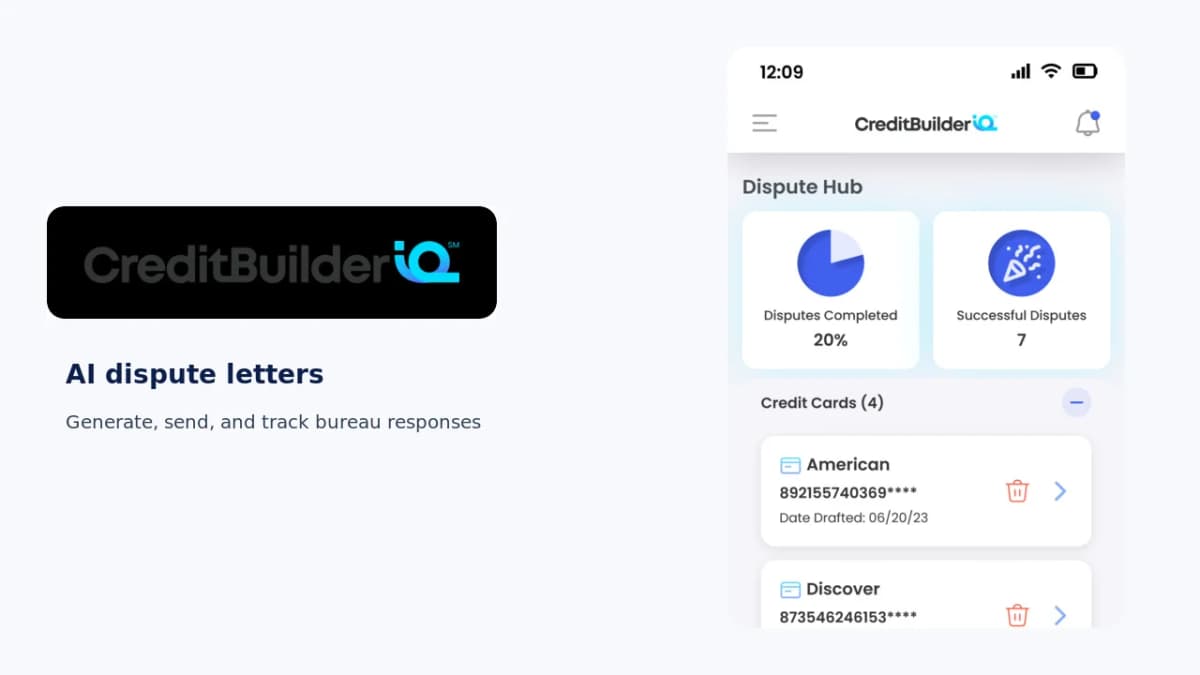
The Dispute Hub is the product’s conversion engine on most promo pages:
- Generate custom letters per bureau for negative/inaccurate items
- Print / mark as sent
- Track status and bureau responses
- Bureaus generally must investigate disputes under the FCRA on defined timelines (often discussed as ~30–45 days)
Critical honesty: Disputing does not lower your score by itself—but disputing accurate negatives usually fails. CreditBuilderIQ helps with process; it does not rewrite federal law. Keep copies of everything you send.
4) Rent, utility & subscription reporting
This is the “build without new debt” hook:
- Rental payment reporting — including historical lookback marketed up to 24 months on official materials
- Utility payment reporting — gas, electricity, water, phone (mobile/landline) called out on utility pages; positive/on-time only
- Subscription reporting — listed on the main site as part of the reporting toolkit
How it typically works for members: link accounts from the portal, identify eligible payments, and let the platform report confirmed on-time payments monthly. Missed/late payments are not supposed to be reported as positive tradelines.
Official and IdentityIQ-family education cites studies such as TransUnion rent-reporting averages and CreditXpert-style “20 points in 30 days” potential indices—results vary; thin files and already-thick files respond differently.
5) Identity protection / dark-web scan
Promo funnels include identity protection and dark-web scanning alongside credit tools. Treat this as a bonus alert layer, not a full Aura/LifeLock/TransUnion Premium identity suite—and still freeze all three bureaus.
Who CreditBuilderIQ is for
Strong fit
- You want 3-bureau visibility without juggling three free apps
- You will actually send disputes for clear inaccuracies (wrong balances, accounts that are not yours, outdated info)
- You pay rent or utilities on time and want them reported
- You prefer DIY software over a $79–$129/mo credit-repair retainer
- You will use the $1 week to decide, then cancel or keep intentionally
Poor fit
- You only want a free FICO habit → CreditWise
- You need a bank installment/revolving tradeline with locked savings → Credit Strong
- You expect a company to “wipe” accurate collections overnight
- You will not open the app after signup (wasted $24.46)
- You refuse freezes and think dark-web alerts replace them
CreditBuilderIQ vs Credit Strong vs free tools vs bureau Premium
| CreditBuilderIQ | Credit Strong | Free stack (Karma + CreditWise) | TransUnion Premium | |
|---|---|---|---|---|
| Core job | DIY scores + disputes + rent/utility reporting | Paid builder tradeline | Habit scores/alerts | 3-bureau watch + ID suite |
| Typical cost | $1 week → $24.46/mo | ~$15–$28+/mo + interest/fees | $0 | ~$29.95/mo |
| 3-bureau scores | Yes (membership) | Score tracking on some plans | Partial across apps | Yes on Premium |
| Dispute letters | AI generation + hub | Not the product | Manual / bureau sites | Limited vs DIY hub |
| Rent/utility report | Yes | No | No | No |
| Creates bank tradeline | No | Yes (installment/revolving) | No | No |
| Best for | Actionable DIY cleanup + alternative data | Thin-file history bridge | Everyday free watching | Continuous fraud monitoring |
Practical combo some readers use: Freeze → CreditBuilderIQ trial to dispute errors + start rent reporting → free CreditWise/Karma for ongoing habits → Credit Strong only if you still need a paid tradeline after cleanup.
How to use the $1 trial like a pro
Freeze Equifax, Experian, TransUnion first
Blocking new fraud matters more than any dashboard. Freeze guide.
Enroll via the trial offer
Confirm $1 / 7 days → $24.46/mo and cancel path on the order summary.
Pull all three scores and download reports
Screenshot mismatches between bureaus.
Run AI analysis — then verify manually
Only dispute items you believe are inaccurate or not yours.
Generate letters and actually send them
Use Dispute Hub tracking. Keep USPS/certified mail receipts if you mail.
Connect rent and/or utilities if eligible
Report only what you pay on time. Update providers if you switch.
Decide on day 5–6
Keep if you are mid-dispute or actively reporting rent. Cancel if the dashboard is idle.
Open CreditBuilderIQ and start the $1 week →
Pros and cons
Pros
- Low-friction $1 / 7-day trial into a clear $24.46/mo price
- Three-bureau scores and reports in one membership
- AI dispute letter generation + tracking hub
- Rent / utility / subscription reporting (positive payments)
- Marketed no hard inquiry to view scores; cancel anytime
- Backed by established IDIQ consumer-finance stack
- Cheaper than many full-service “credit repair” retainers for DIY users
Cons
- Monthly fee adds up if you forget to cancel
- Score gains are not guaranteed; accurate negatives can stay
- You still do the work (send letters, maintain on-time bills)
- Not a substitute for freezes or a bank secured card
- Official retail pricing pages can show different plan prices than the affiliate trial—confirm checkout
- Identity tools are lighter than dedicated ID suites
Common mistakes
- Leaving the trial on autopilot into month 2 unused
- Disputing every negative item blindly (including accurate ones)
- Skipping freezes because “I have dark-web alerts”
- Expecting rent reporting to fix maxed-out cards (utilization still matters)
- Buying CreditBuilderIQ and an expensive repair company for the same disputes
- Confusing this with Credit Strong’s locked-deposit builder loan
Bottom line
CreditBuilderIQ is the strongest fit when you want a DIY credit action plan—3-bureau visibility, AI-assisted disputes, tracking, and rent/utility reporting—at a $1 trial into $24.46/mo. Use the first week to pull reports, start real disputes, and connect eligible bills. Cancel if you will not work the system. Keep freezes on, keep free score apps for habits, and only add a Credit Strong-style tradeline if you still need reported installment/revolving history after cleanup.
Start building with CreditBuilderIQ — $1 for 7 days →
How much does CreditBuilderIQ cost?
The affiliate offer framed in this article is $1 for 7 days, then $24.46 per month, cancel anytime. Confirm the exact trial and renewal price on your checkout screen—official site plan pages may list other prices.
Does CreditBuilderIQ hurt my credit score?
Viewing scores/reports through the service is marketed as no hard inquiry. Disputing itself does not lower your score. Applying for new credit products outside the app can still cause hard pulls.
Is CreditBuilderIQ a credit repair company?
It is DIY software from IDIQ that helps you analyze reports, generate dispute letters, track responses, and report rent/utilities. You remain responsible for sending disputes and for what is accurate on your file.
Can CreditBuilderIQ raise my score 20–50 points?
Marketing cites third-party studies and internal brand research about potential gains. Results vary widely. Accurate negatives, high utilization, and recent late payments limit what any tool can do.
Does rent and utility reporting really help?
Reporting on-time rent/utilities can add alternative payment history for some consumers. Only positive payments are reported. Not a cure for heavy revolving balances or recent delinquencies.
CreditBuilderIQ vs Credit Strong—which should I buy?
CreditBuilderIQ = DIY scores, disputes, rent/utility reporting. Credit Strong = paid bank tradeline that reports installment/revolving history. Different jobs—some people use both carefully, most need only one.
How do I cancel?
Use the account/billing settings or contact CreditBuilderIQ support (customer service email and phone are listed on their site, including 800-321-0215 on Dispute Hub pages). Cancel before the 7-day trial ends if you do not want the $24.46 renewal.
Do I still need a credit freeze?
Yes. Monitoring and dispute tools do not block new credit the way freezes do. Freeze Equifax, Experian, and TransUnion.
Sources and notes
- CreditBuilderIQ affiliate landing, aff/4 preview.
- CreditBuilderIQ, home, pricing, Dispute Hub, utility reporting.
- IDIQ newsroom, CreditBuilderIQ launch (April 16, 2024).
- Promo landers emphasizing $1 week / $24.46 mo feature stacks (e.g. creditscoreads-style funnels).
- SuperMoney directory listing noting $24.46 monthly maintenance (verify live).
- Trustpilot reviews of creditbuilderiq.com (anecdotal; not guarantees).
- CFPB / FTC resources on credit reports, disputes, and freezes; AnnualCreditReport.com.
- Brand marketing claims (20 points / 30 days, 50+ points, rent-reporting averages) come from cited third-party or IDIQ-family studies on their pages—outcomes are not guaranteed.
- This article does not guarantee score increases, dispute wins, rent-reporting eligibility, or fraud prevention.